What is the Direct Drive Motors Market overview and industry significance?
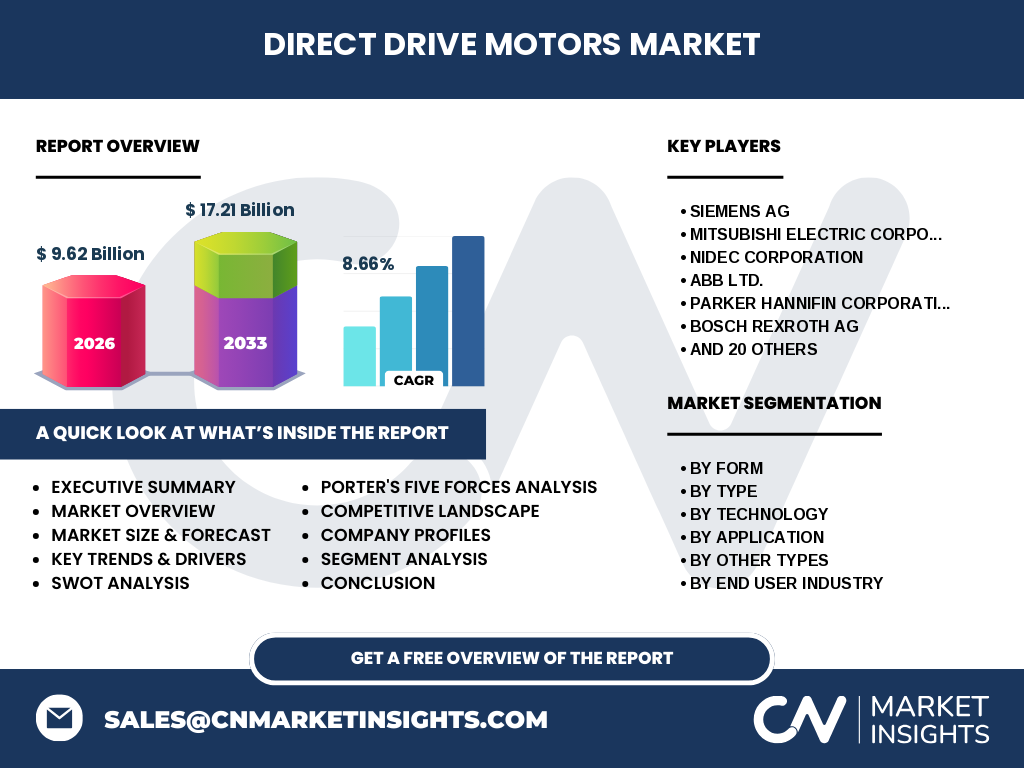
Our analysis indicates that the Direct Drive Motors Market reaches a valuation of 9.62 Billion in 2026. These elimination-of-gearbox systems are critical for high-precision manufacturing, utilizing advanced permanent magnet and linear technologies to achieve unprecedented positioning accuracy across industrial automation.
Key market drivers, restraints, challenges, and opportunities shaping Direct Drive Motors Market
Growth is heavily propelled by demands for zero-backlash motion in robotics. However, raw material price volatility regarding rare-earth magnets poses a restraint. Opportunities abound in high-speed slotted brushless configurations compliant with strict ISO energy efficiency standards.
Emerging trends and growth patterns in Direct Drive Motors Market
The shift toward coreless direct drive motors and slotless configurations is dominating modern engineering design. Industry trends highlight a rapid transition from traditional gear-driven assemblies to compact, high-torque permanent magnet synchronous systems that minimize thermal drift.
COVID-19 impact analysis and recovery trajectory
The pandemic caused severe supply chain bottlenecks for critical copper windings and neodymium materials. Post-crisis recovery has accelerated robustly as automated smart factories prioritize touchless, maintenance-free direct drive technology to future-proof production lines against future labor shocks.
Competitive benchmarking and strategic dynamics
Market concentration remains moderately consolidated among automation giants. Siemens AG, Mitsubishi Electric Corporation, and Nidec Corporation leverage extensive global distribution networks, while specialists like ETEL S.A. and Akribis Systems Pte. Ltd. capture high-end semiconductor niches.
Executive summary of the Direct Drive Motors Market report
Our research underscores a massive expansion phase, projecting the market to surge from 9.62 Billion in 2026 to 17.21 Billion by 2033 at a CAGR of 8.66%. Strategic agility in renewable energy and aerospace sectors will separate market leaders from laggards.
Long-term market forecast from 2027 to 2033
Based on our econometric modeling, the Direct Drive Motors Market will scale aggressively from 2027 to 2033, achieving a total market valuation of 17.21 Billion by the end of the forecast period, driven by an impressive CAGR of 8.66%.
Segmentation analysis across forms, types, and applications
Segmentation spans multiple dimensions: Form includes axial flux, radial flux, and tubular types; Type features brushless, synchronous, and switched reluctance variants; Application covers industrial automation, robotics, medical equipment, and renewable energy installations.
Regional market analysis and geographic distribution
Geographic performance is heavily skewed toward industrial powerhouses in East Asia and Western Europe. Regional constraints, such as stringent EU Ecodesign directives, mandate high-efficiency synchronous motors, directly shaping local manufacturing pipelines and supplier ecosystems.
In-depth regional review of high-growth territories
Asia-Pacific dominates consumption, fueled by aggressive electronics manufacturing in Taiwan, South Korea, and China. Meanwhile, North America exhibits steady adoption within aerospace and defense sectors, relying on domestic innovators like Moog Inc. and Kollmorgen Corporation.
Company profiles and strategic positioning
Industry leaders deploy distinct strategies: ABB Ltd. and Yaskawa Electric Corporation focus on turnkey automation integration, whereas Harmonic Drive Systems Inc. and HIWIN Technologies Corp. optimize ultra-precise motion control components for machine tools.
Porter's Five Forces analysis of competitive intensity
Bargaining power of suppliers is moderate-to-high due to specialized rare-earth magnet sourcing. Threat of substitutes is remarkably low because traditional gearboxes cannot match the dynamic response and zero-maintenance profile of advanced direct drive architectures.
SWOT analysis of the sector
Strengths include exceptional dynamic performance and wear-free operation. Weaknesses involve high initial capital expenditure. Opportunities lie in electric vehicle manufacturing, while threats stem from macroeconomic inflationary pressures impacting industrial capex budgets.
Value chain analysis from raw materials to end-users
The value flow initiates with rare-earth element extraction and high-grade electrical steel production, progressing through motor assembly by firms like WEG S.A. and Danfoss A/S, culminating in deployment across automotive, aerospace, and heavy manufacturing end-user facilities.
Investment insights and strategic recommendations
Investors should target niche innovators specializing in slotless brushless and coreless architectures. High-potential areas include direct drive integration within renewable energy pitch-control mechanisms and ultra-clean medical robotics requiring zero particulate shedding.
Conclusion and key takeaways for stakeholders
The Direct Drive Motors Market represents an indispensable pillar of modern industrial automation. Reaching 17.21 Billion by 2033, success requires strategic alignment with green energy mandates and precision manufacturing advancements.
Research methodology and baseline estimation techniques
Our baseline estimates are rigorously triangulated by combining proprietary trade registry customs data, primary stakeholder interviews with chief technology officers, and secondary macroeconomic indicators published by international manufacturing associations.
Scope of the report and coverage parameters
This report encompasses a comprehensive global assessment of the Direct Drive Motors Market across all specified technological forms, operational types, and end-user verticals, bounded by a historical baseline of 2026 and a forecast horizon extending through 2033.
Recent developments, partnerships, and strategic moves
Recent industry momentum features aggressive R&D investments by Schaeffler Technologies AG & Co. KG and Parker Hannifin Corporation aimed at launching next-generation high-torque density direct drive rotary tables for smart factory applications.