What is the market overview and industry significance of the Embedded Finance And Fintech Infrastructure Platform Market?
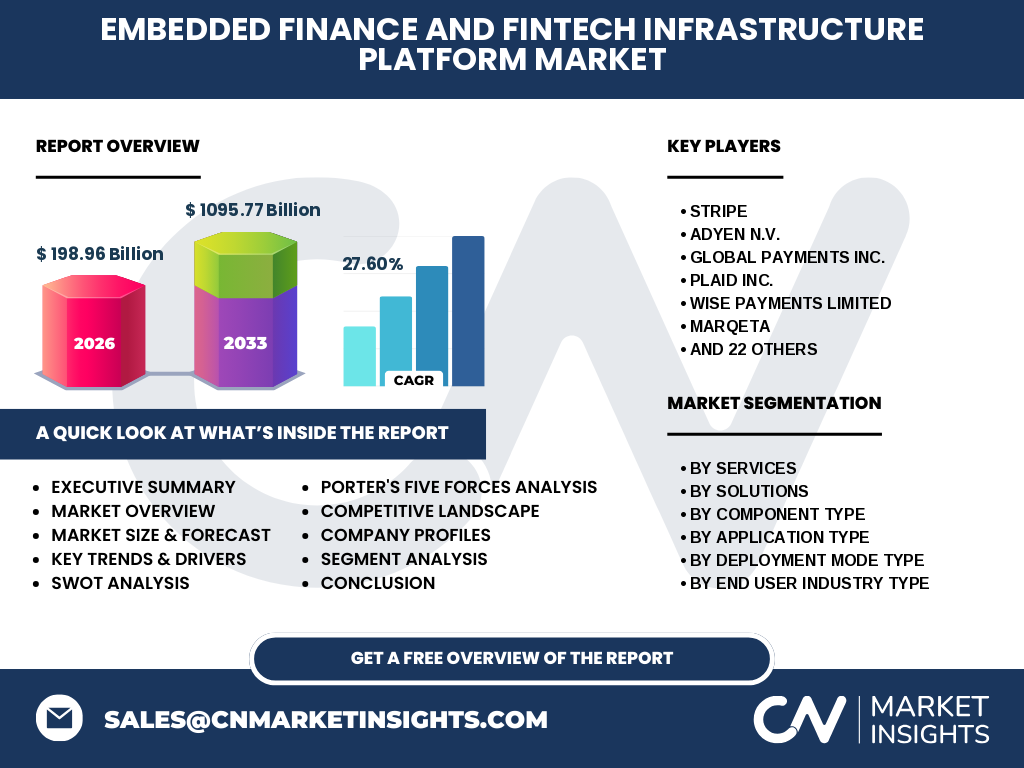
The Embedded Finance And Fintech Infrastructure Platform Market represents a transformative convergence of financial services and non-financial enterprise software. Valued at 198.96 Billion in 2026, this sector enables brands to seamlessly integrate payment processing, lending, and banking capabilities directly into their native digital ecosystems via modular APIs.
What are the structural growth drivers and market restraints shaping this sector?
Our analysis indicates that surging consumer demand for frictionless digital checkout experiences acts as a primary catalyst. Conversely, stringent cross-border regulatory fragmentation imposed by bodies like the CFPB and FCA presents persistent compliance bottlenecks that require sophisticated technological mitigation.
The Shift Toward Modular API Architectures: Emerging trends and growth patterns
Industry dynamics show an aggressive pivot toward decoupled banking-as-a-service layers. Innovators such as Plaid Inc. and Marqeta are leading this evolution by offering granular, developer-first tooling that dramatically compresses enterprise deployment cycles from months to mere days.
How did the COVID-19 pandemic impact the Embedded Finance And Fintech Infrastructure Platform Market and drive its recovery?
The pandemic acted as an unprecedented accelerant, permanently shifting consumer dependency toward contactless digital channels. Post-pandemic recovery has been characterized by accelerated venture investments and enterprise cloud migrations, laying the groundwork for sustained long-term market expansion.
Competitive Benchmarking: Major players and strategic dynamics in the ecosystem
The market exhibits a balanced mix of entrenched giants and agile disruptors. Industry leaders like Stripe and Adyen N.V. compete fiercely with specialized platforms such as Unit Finance Inc. and Synctera Inc. by continuously expanding their comprehensive global acquiring footprints.
Executive Summary: High-level synthesis of key findings for enterprise buyers
Driven by a robust compound annual growth rate of 27.60%, the market is scaling rapidly toward 1095.77 Billion by 2033. Organizations failing to adopt embedded financial workflows risk severe margin compression as native monetization becomes standard across retail and SaaS.
Market Forecast Analysis: Trajectory from 2027 to 2033
Based on our econometric modeling, the sector will experience hyper-growth, surging from baseline 2026 figures to reach a staggering 1095.77 Billion by 2033. This trajectory underscores a permanent structural reallocation of financial distribution channels away from legacy brick-and-mortar institutions.
Segmentation Analysis of solutions, services, components, and deployment modes
The ecosystem is categorized by solutions, services, and deployment modes. Key sub-segments include Payment Processing Platforms, Banking As A Service Platforms, and Cloud Based architectures, which together drive unmatched operational agility across retail and enterprise workflows.
Regional Market Analysis and geographic distribution performance
Geographic performance highlights North America as the dominant revenue contributor, fueled by high venture capital density and progressive open banking initiatives. Meanwhile, Asia-Pacific emerges as the fastest-growing arena, driven by mobile-first super-apps and rapid smartphone penetration.
In-Depth Regional Review of localized regulatory and infrastructure landscapes
European markets navigate rigorous PSD2 and PSD3 frameworks, favoring compliant infrastructure providers like Solaris and Modulr Finance Limited. In contrast, North American growth relies heavily on bank-fintech partnership models championed by entities like Cross River Bank.
Strategic Company Profiles and market positioning strategies
Leading ecosystem participants deploy distinct competitive moats. Galileo and Thredd Group Limited focus on scalable card issuing, whereas Thought Machine Group Limited leverages cloud-native core banking to target tier-one financial institutions seeking modernization.
Porter's Five Forces Analysis of competitive pressures
Threat of new entrants remains moderate due to steep regulatory compliance hurdles and high initial security outlays. However, buyer bargaining power is high, compelling infrastructure providers like Rapyd Financial Network Ltd. to continuously expand their global payout capabilities.
SWOT Analysis of the Embedded Finance And Fintech Infrastructure Platform Market industry
Key strengths include high API modularity and sticky enterprise revenue models. Notable weaknesses involve heavy reliance on traditional sponsor bank networks, while emerging opportunities in healthcare and logistics offer lucrative avenues for expansion against macroeconomic threats.
Value Chain Analysis from underlying data pipelines to end-user applications
The value chain flows from core cloud infrastructure and raw financial ledger data through API middleware layers, ultimately empowering non-financial brands to deliver white-labeled services to end-users across retail, logistics, and digital entertainment sectors.
Investment Insights and high-potential areas for strategic capital allocation
Investors should prioritize B2B embedded lending and automated compliance infrastructure providers. Companies bridging cross-border payment frictions—such as Wise Payments Limited and Finix Payments Inc.—demonstrate superior unit economics and high enterprise retention rates.
Conclusion and Strategic Takeaways for industry stakeholders
The Embedded Finance And Fintech Infrastructure Platform Market is no longer a speculative tech trend but a fundamental pillar of modern commerce. Firms must prioritize API security, robust regulatory compliance, and seamless multi-currency capabilities to capture market share.
Research Methodology: How baseline estimates and market sizes are triangulated
Our research methodology combines rigorous primary stakeholder interviews with C-level executives, exhaustive secondary analysis of regulatory filings from bodies like the SEC, and macroeconomic econometric modeling to establish authoritative baseline figures for the 198.96 Billion market size.
Scope of the Report: Coverage parameters and analytical limitations
This report covers global enterprise adoption trends across twelve distinct end-user industries and two organization size tiers through 2033. Exclusions include purely legacy proprietary banking mainframes that do not utilize modern open API architectures or cloud integration.
Recent Developments: Key partnerships, product rollouts, and strategic acquisitions
Recent market activity is dominated by strategic bank-fintech alliances and international expansion. Innovators like Parafin Inc. and Treasury Prime Inc. have continuously rolled out advanced embedded credit tooling, partnering with major software platforms to capture untapped SME liquidity.