What is the scope and industry significance of the Cleanroom Differential Pressure Gauge Market?
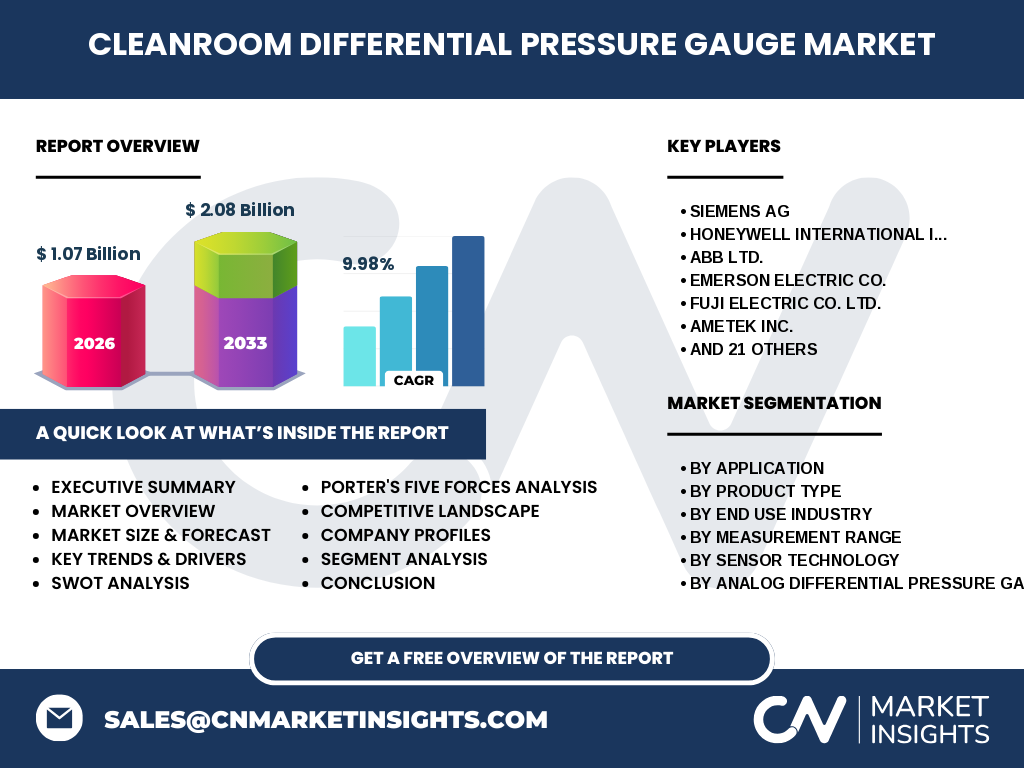
Our analysis indicates that the Cleanroom Differential Pressure Gauge Market size valued at 1.07 Billion in 2026 represents a critical pillar for contamination control. These precision instruments enforce strict air-flow directionality and pressure cascades mandated by ISO 14644 and FDA cGMP standards across sterile manufacturing environments.
Structural Growth Drivers and Restraints
The market is propelled by a 9.98% CAGR through 2027-2033, driven by surging aseptic drug manufacturing and semiconductor fab expansions. Conversely, high calibration maintenance costs and strict metrological compliance present notable operational headwinds for smaller containment facilities.
Emerging Industry Trends in Contamination Monitoring
The transition toward Industrial Internet of Things (IIoT) integration and cloud-connected telemetry is redefining facility monitoring. Operators increasingly favor digital and wireless gauges featuring Bluetooth and LoRaWAN protocols for real-time compliance logging.
COVID-19 Impact and Post-Pandemic Recovery Trajectory
The pandemic catalyzed unprecedented demand for rapid cleanroom deployments within vaccine manufacturing facilities. Supply chain bottlenecks for raw stainless steel and specialized sensing diaphragms accelerated the shift toward localized, high-precision digital monitoring devices.
Competitive Landscape and Strategic Dynamics
Market concentration is characterized by a blend of legacy instrumentation giants and specialized metrology innovators. Industry stalwarts like DwyerOmega, WIKA, and Setra Systems leverage extensive global distribution networks to maintain dominance in high-purity pharmaceutical sectors.
Executive Summary of Key Analytical Findings
Driven by expanding biologics and microelectronics production, the Cleanroom Differential Pressure Gauge Market is projected to reach 2.08 Billion by 2033. Continuous technological integration of capacitive and thermal sensors remains the primary value catalyst.
Market Forecast and Long-Term Projections (2027 to 2033)
Our forecast models steady acceleration from the 2026 baseline, achieving a robust 9.98% CAGR through 2033. This trajectory reflects compounding investments in sterile processing suites, advanced research laboratories, and aerospace cleanrooms globally.
Comprehensive Segmentation Analysis
The market breaks down across applications like Cleanrooms and Laboratory Monitoring, product types including analog and digital gauges, end-use sectors ranging from pharmaceuticals to aerospace, and diverse measurement ranges and sensor technologies.
Geographic Distribution and Regional Market Performance
North America and Europe currently dominate consumption due to stringent regulatory enforcement by the FDA and EMA. Meanwhile, the Asia-Pacific region exhibits the fastest growth velocity, fueled by expanding semiconductor foundries and biomanufacturing hubs.
In-Depth Regional Review of High-Growth Hubs
Regional performance is heavily tied to domestic life sciences and tech manufacturing investments. APAC markets in particular show exceptional promise, driven by government incentives for localized pharmaceutical production and advanced electronics fabrication.
Company Profiles and Strategic Positioning
Key participants such as Siemens AG, Honeywell International Inc., and Emerson Electric Co. focus on integrated building automation systems. Meanwhile, specialized firms like MKS Instruments and DwyerOmega target high-precision ultra-clean environments.
Porter's Five Forces Competitive Assessment
Industry rivalry is intense, tempered by high switching costs associated with validated pharmaceutical equipment. Supplier power remains moderate, restricted by the specialized metallurgical and calibration requirements for ultra-high pressure and capacitive sensor components.
SWOT Analysis of the Industrial Ecosystem
Strengths lie in high measurement accuracy and regulatory compliance. Weaknesses involve complex calibration cycles. Opportunities emerge in wireless IIoT upgrades, while threats include low-cost analog alternatives and supply chain disruptions for electronic components.
Value Chain Analysis from Raw Materials to End-Users
Value creation flows from high-grade raw material sourcing (such as 316L stainless steel) through precision sensor manufacturing and automated calibration, culminating in integration with facility HVAC systems and pharmaceutical end-users.
Strategic Investment Insights and High-Potential Areas
Investors should prioritize manufacturers of wireless and IoT-enabled differential pressure gauges. These segments capture premium margins by directly addressing the pharmaceutical industry demand for automated, paperless environmental monitoring systems.
Conclusion and Strategic Takeaways
The Cleanroom Differential Pressure Gauge Market represents a high-barrier, compliance-driven sector poised for substantial growth. Success hinges on embracing digital sensor technologies and securing long-term service contracts with biopharmaceutical giants.
Research Methodology and Data Triangulation
Our analytical framework triangulates data from customs trade registries, primary stakeholder interviews with metrology engineers, and secondary macroeconomic indicators to establish precise market sizing and growth projections.
Scope of the Report and Analytical Limitations
This report covers global market dynamics for differential pressure gauges utilized strictly in controlled contamination environments. Limitations include inherent delays in official trade statistics and regional variations in calibration standards.
Recent Developments and Industry Innovations
Recent strategic moves emphasize product launches featuring cloud-connected telemetry and battery-powered wireless capabilities. Industry leaders are forming targeted distribution partnerships with HVAC system integrators to streamline cleanroom installation workflows.